


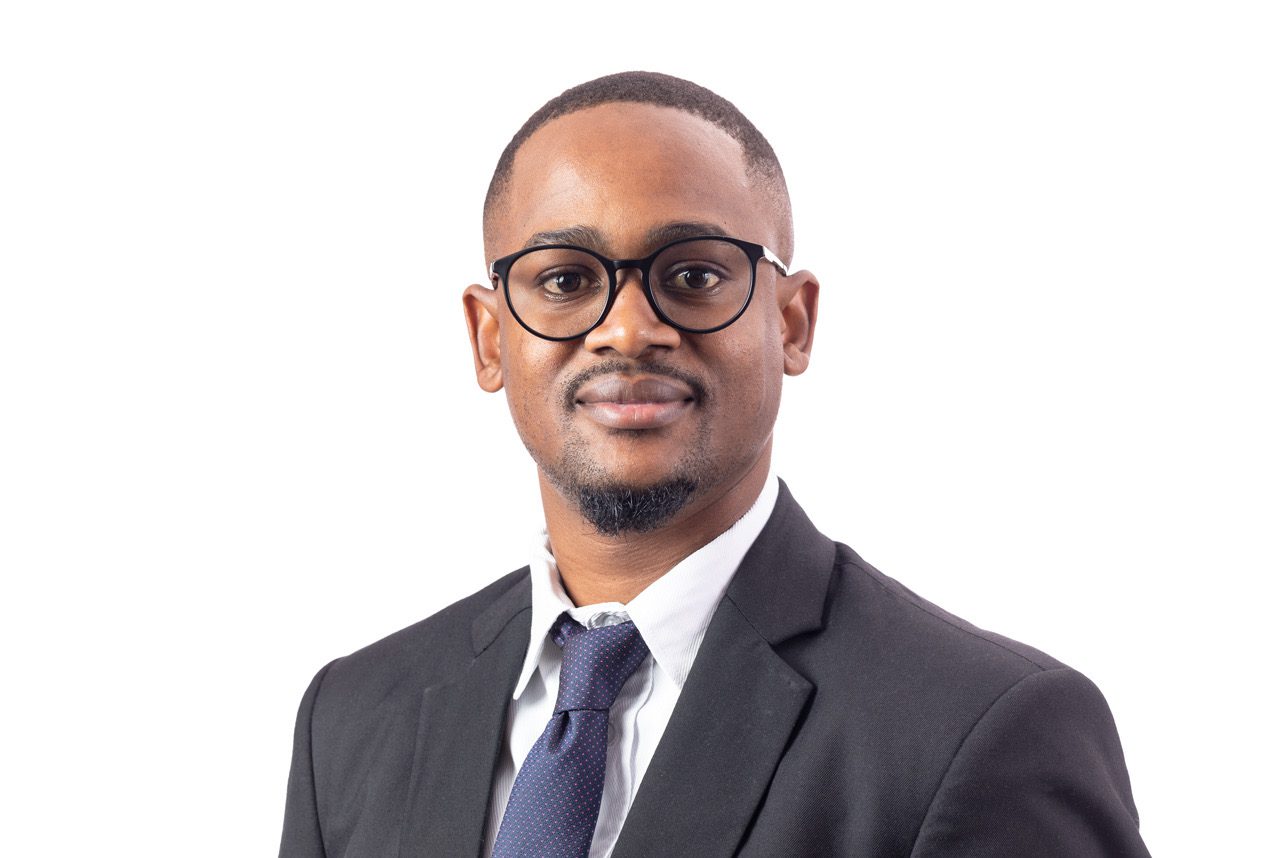
Absa Bank Botswana is not asking the informal economy to fit into banking. It is reshaping banking to fit into the daily life of the hustle.
That is the philosophy driving Grant Maokanyane who heads the bank’s Card and Payments function, a mandate that spans card issuing, your everyday debit and credit cards, and card acquiring: point-of-sale devices, e-commerce gateways and cross-border payments.
His mandate is to enable clients to either accept or issue payments in a seamless way, thereby fitting into the broader agenda of the bank, and of the economy, around digitisation.
It is a role that sits at the heart of Absa’s pivot from an interest-income-led model to a diversified, non-interest revenue future. Before leading payments, Maokanyaneheaded Strategy and Business Transformation in what was then Retail Banking, now Personal and Private Banking, a journey he started in 2020.
“At that time the bank was largely interest income led, and we were resetting that journey towards diversifying revenue pools and growing non-interest revenue, while driving customer primacy and digitisation,” he recalls. It was during that transformation that Absa’s digital wallet, Spark, was born.
The product thinking, however, started earlier. Maokanyane joined Absa as a graduate trainee, understudying as a product manager in unsecured lending, crafting credit policies and learning the intimate nuggets of personal lending, credit risk, customer journeys and product development.
Academically a Chartered Accountant with CIMA, he started his career in 2015 at Nashua Botswana as an intern and then accounts assistant for two years before joining the bank; notably, not in finance.
“I’ve always had a passion for making money. Even when I was at school, I used to love selling things, he says.
He brings that trader’s instinct to banking.
The product he is most animated about today is Absa MobiTap, launched in June 2023 as a first-of-its-kind in Botswana.
The gap it set out to close was simple and stark: point-of-sale devices were built for larger businesses, while the real heartbeat of the economy; SMEs, market vendors, taxi operators, farmers’ markets, food markets, e-hailing drivers; lives on mobile phones.
“Why can’t we turn this thing into a payment acceptance device?” he asks, in rhetoric.
If you have an Near-Field Communication (NFC)-enabled Android phone, you download the Absa MobiTap app, Absa configures it on the back-end, and your phone becomes a till that accepts both card and mobile money. With almost 98 percent of cards globally and locally now tap-enabled, the behaviour already exists.
And for those without a compatible phone, exclusion is not an option.
“We issue out a device to you on a rental basis, because you shouldn’t be excluded just because you don’t have the right gadget in your pocket,” Maokanyane says.
It was a deliberate focus on where cash still dominates and where pain is highest. “We looked at taxi operators, markets, vendors;farmers markets and various food markets booming; your e-hailing guys, your hustlers and said, these are the people that we want to enable.”
That insight led to the partnership with the Yellow Light Taxi Association, launched in early August this year. Cash moves heavily in the transport industry, but cash also carries risk and exclusion.
“When we had the engagement with the Yellow Light Taxi Association executive committee, they highlighted that taxi operators are typically excluded from banking services despite handling a lot of cash. People know that they handle a lot of cash. So there’s also a risk to it,” Maokanyane says, adding that accepting card payments mitigates theft.
Absa did not launch from a boardroom. It went to BBS Mall and Gaborone station where the taxis are.
The team stationed itself there for the whole day. Operators engaged, asked questions, handled the device, signed up and were onboarded on the spot.
But MobiTap is not just a product, it is a partnership designed around two deeper pain points. First, cash is unsafe. Second, cash is easily misused.
So every MobiTap comes with a transactional account and a debit card. When a customer taps, the money lands directly into the taxi operator’s account. Around that, Absa is layering financial literacy, working with the association to package lessons on money management and the importance of saving.
Crucially, MobiTap is only the start. It is how the bank builds a relationship and a transaction history, and then builds a growth path.
“Today, if I want to buy another taxi, if I don’t have the money, I’ll go to someone who has the means. And they’ll say, okay, I’ll buy the taxi for you. You’ll pay me 300 pula on a daily basis. And when we calculated that, it was going up to four or P5,000 pula,” operators told him. They were paying it.
“So we said, if this guy can afford to pay P5,000 to someone, it means they are doing a lot more.”
Absa’s response was a financing of up to P60,000 with monthly repayments below that P4,000, enabling operators to own rather than rent their growth. The bank is now piloting further cash-flow solutions, overdrafts of up to P5,000 over 12 months for MobiTap users who have transacted well for six months, with monthly interest of less than 5 percent charged only on the amount utilised.
Interoperability is the next frontier. Through MobiTap, Absa has enabled mobile money acceptance, starting with Orange Money, withother issuers are coming.
“You have Orange Money, you want to pay a vendor who doesn’t have Orange Money but has the device. He will simply enable you to move money directly from the Orange Money wallet into the merchant’s bank account,” Maokanyane explains.
Launched with Orange Money last November and now scaling, it directly answers government’s call for systems that talk to each other. Similar engagements have already been held with vegetable and fruit vendors in BBS to onboard, teach and digitise.
The uptake is telling. “MobiTap is doing really well, incredibly well. In the market today, we have well over 2,000 devices. You go around town, you’ll see various vendors pull out the small red machine or on their phones, accepting payments. It’s selling like fat cakes,” he says.
Simplicity is why. The device works like a phone. The merchant uses a personal password for security, and sees two clear menus: card acceptance and mobile money acceptance.
For cards, click card acceptance, enter amount, customer taps, screen shows approved. The merchant can send an SMS or email receipt and view transaction history,successful transactions and more, at a glance.
For mobile money, select the mobile money icon, select Orange Money, enter the payer’s mobile number and amount, send a request, and the payer authorises just as they would with a PIN. The funds move directly into the merchant’s account.
Behind it is a support team whose daily mandate is to keep the little red machine working, plus an inclusive data model.
“The device uses network and we fully foot that bill. It also uses Wi-Fi if someone wants to connect it. Even on the app that you would have downloaded on your own device, we have actually zero-rated that app. So it works seamlessly without the merchant having to pay for that cost,” Maokanyane says.
For the user, especially in the informal sector, the benefits are safety, tracking of financial history, and never losing a sale. For the bank, the benefits are just as tangible: converting floating cash into the banking ecosystem provides liquidity; rental fees of P75 per month, less than P3 per day, generate non-interest revenue; transactional activity drives debit card usage, fuel and stock purchases; and lending generates net interest income.
Absa is also exploring embedding its bancassurance brokerage, risk management and insurance products, into the same partnership.
All of these matter because Botswana is digitising fast. Citing FinScope studies, Maokanyane notes financial access has grown from 69 percent of adults in 2009 to 94 percent in 2024, with mobile money driving exponential inclusion. “Hence why we’ve decided to partner with them and not think of them as competitors.”
Data is the dividend. “It enables us to create some sort of footprint and history and generate data. And through those data points, we get to understand the needs of our customers, and thereby develop various products and solutions.”
Cash will remain, he is quick to add, but digitisation is at the forefront of the future economy.
That is why Absa’s design principle is inverted: “We are not asking informal businesses to fit into banking. We are trying to change banking to fit into their daily lives. We are not even asking for payslips, we are not asking for audited results. We are going to use the data points that we have to craft products for our informal merchants.”
The doors, he says, are open. “There are various groups out there that we can partner with. Our country is at a pivotal time, going through a structural change, and it’s for us to hold it at the front to lead with some of these solutions.”
To drive adoption, Absa is running two flagship campaigns. An SME campaign, which started at the beginning of September and runs for three months, rewards SMEs who open an Absa business account, get an Absa business debit card and transact P2,000 ten times in a month with a chance to win P75,000; three winners in total. There is the Win a Moraka campaign, which encourages a culture of saving through current or savings accounts, with grand prizes of cattle and a bull, plus monthly and quarterly small stock prizes.
From a red device at a taxi rank to a tap on a phone in BBS Mall, the message is the same: digitise the payment, formalise the history, finance the growth.


