


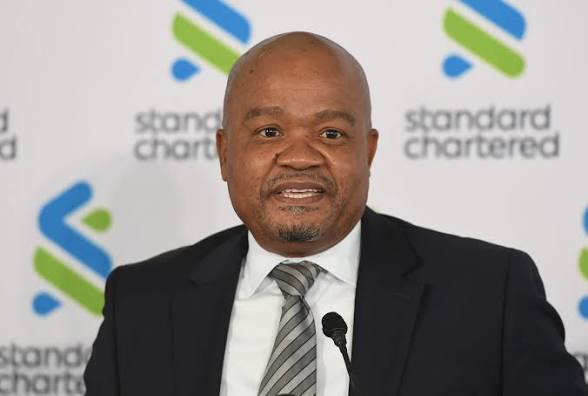
As Standard Chartered Bank Botswana prepares for a quarter four (Q4) change of shareholder, CEO Mpho Masupe and CFO Tapiwa Butale reveal a single, elegant playbook: protect the balance sheet, grow fee income, diversify beyond diamonds, and keep talent, delivering a 22percent ROE, 19 percent capital and 22percent profit growth in the process. Staff Writer KEABETSWE NEWEL reports
There is a particular art to selling something without diminishing it. Most sellers spruce up the shop window. Standard Chartered Bank Botswana is doing something rarer: it is preserving the entire house, brick by brick, while it negotiates who gets the keys.
“We run a very resilient bank. We have gone through serious turbulence, but we have remained resilient and we continue to remain resilient to ensure that we can eventually sell what we consider to be a great bank,” said Chief Executive Officer Mpho Masupe at the bank’s half-year results briefing in Gaborone.
“A great bank to the bidder is what the bidder defines. A great bank to us is what we define, to ensure that everything that we have been doing in the right way continues throughout the transition.”
That definition, laid out by Masupe and quantified by Chief Finance Officer Tapiwa Butale, is now visible in both strategy slides and the income statement. Profit before tax is up 22 percent to P171 million. Return on Equity has doubled from around 10 percent four years ago to 22 percent at June. The non-performing loan ratio sits at 1 percent against a market average of 3 percent. Capital adequacy stands at 19 percent against a regulatory floor of 12.5 percent. And the share price, Butale noted, has been inching up in real time, from P8.76 at June 30 to P8.77 the day before the briefing, “further reflecting confidence that our investors have on the bank’s strategy.”
The market is not rewarding a bank in retreat. It is rewarding a bank that chose preservation over panic.
The Custodian’s Promise
Masupe does not speak like an executive closing a chapter. He speaks like a custodian handing over an heirloom.
Botswana’s oldest bank arrived in 1897, when it was still Standard Bank, a lineage that causes the occasional mistaken identity.
“I do know that when you meet a Standard Bank person anywhere and you call them Standard Bank, they get very unhappy. But there is an advert there that says come and bank with Standard Bank. At a time when we had not as yet been separated, it was Standard Bank,” Masupe smiled. “It’s something that we are very proud of. We stand on the shoulders of giants who have come before us.”
He invoked images that still resonate in branches: aircraft flying into Kanye and other districts to distribute government money, mobile vans threading small villages. That legacy, he said, must be present in the handover.
“We want that legacy to live in our minds as we hand over this bank to whichever the bidder will be.”
The strategy he put to the board for this transition is disarmingly simple: preserve the business, retain the people, protect the risk.
“We have gone out to put together some kind of strategy that we are going to work with during this transition. And that strategy is quite simple and quite clear. We want to be able to preserve the business throughout the operation. We do not want a situation where everybody begins to leave, clients leave, employees leave and we begin to have problems,” Masupe said.
It is why attrition remains, in his words, “very, very low away” from the 10 percentindustry benchmark, even in a sale process. And it is why the bank has gone to unusual lengths to define what is actually being sold.
“The story of the sale of this bank is this. We are only changing shareholders. Now that you are selling the whole bank, you are only changing shareholders to the extent that this particular shareholder gets out and this shareholder comes in and then the bank still continues to run assets,” he clarified.
“I think this is quite important because when we had the conversation at our full year results, people believed that we are going to franchise and that is not the case.”
On timing, Masupe confirmed the Botswana Stock Exchange announcement that the bank is in deep, exclusive conversations with a bidder to agree terms.
“We had hoped to have announced to yourselves exactly who we are talking to and what has happened but we have not done that as yet. But we believe that we should be able to do it in Q4,” he said. “We are now in what we believe is the last mile of this particular conversation.”
He knows the choreography from the inside. Standard Chartered has executed more than 10 similar transitions globally. The non-negotiable, he said, is operational perfection on crossover weekend.
“We do not want on the weekend that we cross over to the new bank to have your card not working as it should. To have your balance different from what you knew it the night before. We can’t have situations like that,” Masupe said.
“The name of Stanchart cannot be allowed to be dragged down as a result of 10 customers in Botswana having their balances being different in their new card that they have been given by a new bank. We cannot afford that.”
How Preservation Became Performance
If Masupe provided the why and the how of preservation, Tapiwa Butale provided the mathematical proof that it works.
Protecting Shareholder Investment Became 22 percent ROE
“A key component of our strategy is on maximising or on protecting shareholder investment. And one measure that we always use within the bank to be able to demonstrate that is the return on equity. You all know that some four years ago this was tracking at around 10 percent,” Butale said.
“And now we are delivering a strong double digit return on equity. We closed as of June at 22 percent, with a further increase when you compare to when we were last year.”
Protecting The Balance Sheet
In a year of expensive funding, Standard Chartered made a counter-intuitive call: shrink deposits by 10 percent.
“Yes, it’s a deliberate reduction, looking at the liquidity levels that we had as at the time to ensure that we balance the level of liquidity that we bought, also looking at the level of lending that we were able to deliver,” Butale explained.
Retail loans and advances had fallen 11percent after proactive portfolio actions in Q4 last year, tightening lending criteria to avoid vulnerable segments. Holding excess deposits against a muted book would have been costly.
“From a retail perspective, you will note that there was a notable decline of about 11 percent in terms of balance sheets, loans and advances, so it also made quite a lot of sense for the bank to continue to reposition the funding structure to ensure that we don’t continue to hold excess liquidity.”
This is Wealth and Retail Banking’s mandate under the transition strategy, Masupe had said earlier: “protect the balance sheet, grow fee income, retaining our clients, strengthening controls.”
Diversifying Beyond Diamonds Meant Growing Corporate 100%+
While retail shrank, Corporate and Investment Banking grew loans and advances by over 100 percent year-on-year. Overall customer loans still grew 5percent.
“But now looking at the corporate side, they were able to increase the loans and advances year on year, quite comfortably reporting over 100 percent increase on the assets and that also aligns to the engagements that we had to say there is quite a lot of appetite, we do have quite a lot of capacity to be able to continue to support economic activity,” Butale said.
That aligns directly to Masupe’s second mandate for CIB: fix the liability mix, cheaper, long-staying deposits that can be lent longer, and diversify the portfolio.
“One realises when the diamonds have done what they have done that you don’t really want to be overexposed to that one industry,” Masupe said. “It just means that you grow the rest of the other avenues that are not within the diamond industry.”
The bank’s support for government, energy and telecommunications in the halfyear is evidence of that diversification in action.
Growing Fee Income Meant 64 percentGrowth When Interest Income Fell 14percent
Here lies the elegant pivot that explains how profit rose while revenue fell 3percent.
Net interest income declined 14 percent, hit by both the smaller retail book and the expensive deposits picked up late last year. Butale noted funding costs are now easing, market asset-to-deposit ratio improving from 99 percent to 91 percent in the past three to four months, and those expensive deposits should roll off by year-end.
Meanwhile, non-funded income surged 64percent year-on-year.
“When we last spoke to you we said that during this difficult time we also want to pivot towards non-funded income performance. And now looking at the half year results, non-funded income contribution to total income has improved quite significantly,” Butale said, crediting wealth management and deposit fee income as stability returned.
Retaining Talent Meant Holding Costs To 1percent Through Digital
Costs rose just 1 percent, remarkable in an inflationary environment, and that increase, Butale said, was investment in people.
“That increase is mainly coming out of our investment on our people. We did quite a lot of reviews, in terms of ensuring that we retain our talent,” he said.
The underlying control comes from years of digital investment.
“Now what we’ve noted within the bank is that the cost to serve our client has reduced quite significantly. And that is a result of the digital investment that we did over the years, such that now when one expects for costs to be relatively elevated we are able to have a good handle in terms of our costs, because most of our processes have now been digitalised.”
Masupe’s cost-to-income ratio of 62percent, up from 59 percent, is therefore not a slippage, Butale argued, but a denominator story: “That’s not a reflection of non- performance, but a factor of our top line performance, which declined.”
On impairments, the 1 percent NPL ratio tells its own story. Despite 5 percent loan book growth, impairments were well controlled, and last year’s charge had included a one-off duplicate interest in suspense item.
“We do have one of the good performing books within the country,” Butale said. “That compares quite favourably with market average, which normally tracks between 3 percent and 4 percent.”
And the capital to keep doing it, at 19percent, remains comfortably above the 12.5 percent regulatory limit.
What binds strategy to numbers is people. Masupe is explicit: what the bidder is buying is not just a loan book, but talent.
“We have gone out and looked at our reward system and ensured that there is something in it for them. We don’t only pay you top dollar now but we want to make sure that if you stay with this bank, there is something waiting for you when the transition has happened,” he said.
Critical employees have bespoke plans. All have been given assurance of continuity, Masupe said bidders have offered 2 to 3 years of job security , and a broader ecosystem of care: mental health systems on phones and laptops, direct counselling, including counsellors outside Botswana for privacy, five months paternity leave still honoured, and up to 90 days leave for chronic illness, more generous than the new Employment Act, which the bank already exceeds.
“Possibly leading to more hardships for our people in the country and we will not work like that, we have never worked like that in a long time,” Masupe said at the briefing, explaining why resilience matters.
The final glue is learning. On its DiSCOVER platform offering Duke and INSEAD-accredited courses, uptake sits at 93 percent, one of the highest in the Group. Staff are studying AI, project management, digital and wealth management at home.
“It is not all of us that are motivated or that stay because of money,” Masupe reflected. “As I go around the country talking to branches there is some kind of purpose.We are basically transitioning a historical bank that has been in the country for 129 years and ensuring that it gets a good buyer so we become part of history as we do that.”
That is the alignment. Masupe’s strategy to preserve the business, retain talent and protect risk is not a slide deck for a sale. It is Tapiwa Butale’s P171 million profit, 22percent ROE, 1 percent NPL and 19percent capital. It is the deliberate 10percent deposit shrink that protects margins, the 100 percent corporate growth that diversifies away from diamonds, and the 64 percent fee income surge that offsets interest pressure.
Standard Chartered Botswana is proving that the best way to sell a great bank is to keep running it like a great bank, until the very last day, and ready for the next 129 years.


